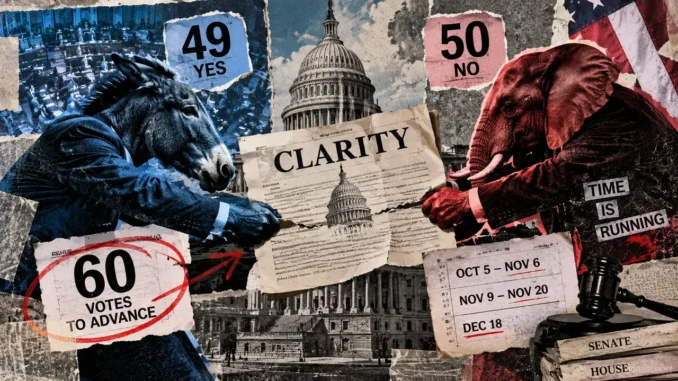
Seven Democratic senators said Sept. 16 that CLARITY’s failed Senate vote was not the end. The crypto market-structure bill fell short 49-50 the previous day on a procedural motion that needed 60 votes to advance.
Getting from that statement to a law now depends on a compressed legislative calendar, still-unresolved policy disputes, and a House of Representatives that would need to accept whatever the Senate eventually produces.
Even if all seven signatories switched from “No” to “Yes,” the count would move from 49 to 56, four short of 60. Adding North Carolina Republican Thom Tillis, whose “no” vote was a procedural move preserving his ability to bring the measure back for reconsideration, would push the total to 57, still three votes shy.
The statement shows real political will to keep negotiating, but it falls far short of describing a coalition capable of clearing the floor.
ScenarioYes VotesStill Short of 60What It ShowsSept. 15 cloture result4911The bill failed to advanceSeven Democratic signatories switch to yes564Their support alone would not be enoughSeven Democrats plus Thom Tillis switch573Tillis helps reopen the path but does not solve itMinimum needed for cloture600Supporters still need a broader deal
Getting CLARITY passed requires clearing several separate gates
Tillis’s procedural “No” gives Senate leadership a live vehicle to bring CLARITY back. From there, the Senate would first need 60 votes to formally proceed to the bill, a step distinct from passing it.
Once CLARITY is on the floor, leadership must decide whether the negotiated text stays locked or opens to floor amendments, since ethics, stablecoin, and consumer-protection language could all be rewritten during that window.
Opponents can then mount a second filibuster against the underlying bill itself, meaning supporters may need 60 votes twice over before a simple majority can finally pass it.
Passage in the Senate would still leave the House needing to accept that text or negotiate a reconciled version, since both chambers must approve identical language before it ever reaches the president’s desk.
A state work period runs from Oct. 5 through Nov. 6, leaving only the days before that recess for an immediate attempt to pass CLARITY, and no confirmed agreement exists to fill that window yet.
The chamber returns for a stretch from Nov. 9 through roughly Nov. 20, competing directly against nominations, appropriations, defense authorization, and tax legislation for scarce floor time.
A Thanksgiving break follows before a final push toward the Senate’s Dec. 18 target for adjournment, a soft internal marker well short of a hard legal cutoff, since the current Congress technically runs into early January 2027.
Any Senate action inside that final stretch would still need to reach the House with enough time left for identical text to clear both chambers before the session effectively winds down.
GateWhat Must HappenMain RiskReconsideration or renewed floor attemptSenate leadership brings the measure backNo confirmed agreement or scheduleCloture on motion to proceed60 senators agree to start formal considerationVote count still shortFloor managementLeaders decide whether text is locked or open to amendmentsEthics, stablecoin, and consumer language could reopenCloture on the bill itselfSupporters may need 60 votes again to end debateSecond filibuster pointSenate passageBill clears the chamber after debate endsFinal text may differ from House versionHouse actionHouse accepts or reconciles Senate textCalendar may be too compressedPresidential presentmentBoth chambers approve identical languageCannot happen until House-Senate text matches
What a workable deal has to resolve
Republican sponsors say their latest draft folds in 126 changes Democrats requested, including new ethics restrictions tied to presidential crypto holdings and a Treasury mechanism meant to respond to stablecoin-related deposit flight.
Democratic negotiators, including Mark Warner and Ruben Gallego, have continued flagging unresolved objections specifically about President Donald Trump’s crypto interests. The ethics language exists but has not yet satisfied the senators whose votes matter most.
Banking associations separately argue the Treasury backstop responds only after harmful deposit flight has already occurred, and are pushing for tighter limits on the underlying stablecoin rewards themselves.
A July statement from Democratic negotiators also flagged consumer protection, illicit finance and market-integrity provisions as insufficient, and nothing in the September statement specifies which of those objections have since been resolved.
If Congress cannot finish this in 2026, federal regulators can still fill parts of the CLARITY gap through existing rulemaking authority. That kind of agency action is far less permanent than a statute passed by Congress, and other jurisdictions are moving ahead regardless.
The European Union’s transition period for crypto-asset service providers under MiCA ran through July 1, giving European firms a completed framework while the American process remains open-ended.
IssueCurrent Status in ArticleWhat Would Signal ProgressEthics restrictionsNew language exists, but key Democrats still object to Trump-related crypto interestsRevised text that Warner, Gallego, or other holdouts publicly acceptStablecoin rewardsBanking groups say the Treasury backstop acts too lateTighter reward limits or a revised backstop acceptable to banks and senatorsConsumer protectionDemocrats flagged earlier deficienciesClearer investor-protection language in the next draftIllicit financeStill listed among unresolved Democratic concernsUpdated compliance or enforcement provisionsMarket integrityConcerns remain around conflicts and trading rulesStronger market-structure safeguardsHouse alignmentSenate changes may differ from House-passed textHouse leadership signals willingness to move the Senate version quickly
The window is closing quickly
The bull case has a revised ethics and stablecoin agreement landing before the Oct. 5 recess, locking in the seven signatories, Tillis and several additional senators at once.
Under that path, Senate leadership can schedule reconsideration either just before the break or immediately upon return in November.
CLARITY’s remaining test becomes a House execution problem well beyond a Senate vote-counting one, since the chamber would then need to move quickly on whatever the Senate sends over.
The bear case has negotiations still unsettled when the Senate returns Nov. 9, with ethics and stablecoin language remaining the sticking points while floor time gets consumed by other must-pass legislation.
In that scenario, any eventual Senate agreement arrives too close to the Dec. 18 target for the House to act on identical language in time, and CLARITY carries into the next Congress as an unfinished project well short of a completed law.
The clearest signs that CLARITY is moving again will be a public revision to the text, a named coalition of senators beyond the current seven, and a scheduled reconsideration or cloture vote.A House willing to act on whatever the Senate eventually sends its way would complete the picture.


